
The 6 Best Lenders for Loans for Bad Credit in 2026
Last updated: 2026-11-09
Walking through a financial storm without an umbrella is a feeling most people know too well. When your credit score isn’t a polished masterpiece, finding a lifeline feels like searching for a needle in a haystack. You might just need a bridge to get from a sudden emergency to your next paycheck.
Maybe your car’s transmission just quit, or a dental bill arrived out of nowhere. Perhaps a sudden spike in utility costs has left your budget in the red. These moments of volatility demand quick action. More importantly, they require you to make smart, informed decisions under pressure.
Finding the right lender involves more than just chasing the fastest cash. You have to keep a sharp eye on the fine print, the speed of funding, and whether a company actually cares about your history. A lender promising lightning-fast cash while hiding a 400% APR in a footnote is a trap, not a lifeline.
This list highlights the most reliable options available today. It is meant to help you tell the difference between genuine financial tools and predatory lending schemes that aim to exploit your situation.
- Lending Point
- JetzLoan
- MoneyLion
- OppLoans
- Check City
- Lend You Cash
How These Lenders Were Evaluated
Our selection process focused on two things: transparency and accessibility. We looked closely at every option to see if they truly serve people with less-than-perfect credit. Offering money is one thing, but a lender must provide a clear path to repayment. You shouldn’t have to dig through a mountain of fine print to find the true cost of your capital.
We looked specifically for lenders that use “soft credit pulls” during the pre-qualification stage. This lets you shop around without damaging your score before you even know if you are approved. It is a vital distinction for anyone trying to protect their credit while exploring their options.
Speed and the impact on your credit score were also vital metrics. Some lenders allow you to check eligibility without leaving a permanent scar on your report. Others prioritize getting funds into your bank account by the next business day to handle urgent medical or home repairs.
We weighed the trade-offs between high-interest, high-speed short-term loans and lower-interest, slower-moving personal loans. This provides a spectrum of options for every level of urgency, from immediate crises to planned financial restructuring.
| Lender Name | Loan Amount Range | Funding Speed | Credit Impact | Special Features |
|---|---|---|---|---|
| LendingPoint | $1,000 – $36,500 | See site | No impact on score | Debt consolidation focus |
| JetzLoan | See site | See site | See site | See site |
| MoneyLion | Up to $100,000 | Fast/Expedited | Build credit options | Cash advances available |
| OppLoans | See site | Same-day available | No impact on FICO | 5-star marketplace rating |
| Check City | See site | See site | See site | Payday & installment options |
| Lend You Cash | Up to $1,000 | Next business day | See site | Installment loans |
Understanding the Real Cost of Borrowing
Before you dive into specific lenders, you need to understand the math. Most borrowers make the mistake of focusing on the “monthly payment” instead of the “total cost of credit.” This tiny distinction can be the difference between a manageable setback and a long-term debt spiral.
Think about a $2,000 loan. If you take a 12-month installment loan at 15% APR, your total interest might be around $165. However, if you take a short-term payday loan for that same $2,000 with a much higher APR, the total interest and fees could easily exceed $500. You are paying much more just for the privilege of a shorter window.
When you compare lenders, always ask for the Truth in Lending Act (TILA) disclosures. These require lenders to clearly state the total finance charge. It tells you the actual amount you will have paid back by the end of the term, so there are no surprises when the final bill arrives.
You must also differentiate between “hard” and “soft” credit inquiries. A soft inquiry occurs when a lender checks your credit to see if you qualify. This doesn’t affect your score. A hard inquiry happens when you officially apply, which can cause a temporary dip of 5 to 10 points.
Always use lenders that offer pre-qualification via soft pulls. It protects your score while you are still in the “window shopping” phase. You can see your options without risking your credit standing before you even know if you want to move forward.
Top Ranked Credit-Challenged Lenders
1. LendingPoint
LendingPoint acts as a sophisticated partner for people trying to clean up their financial slate. They offer substantial amounts, ranging from $1,000 up to $36,500. This makes them a strong contender for anyone facing a heavy debt load or significant medical expenses that need immediate attention.
Unlike many “subprime” lenders that only offer small, high-interest micro-loans, LendingPoint provides the headroom necessary to actually make a dent in existing debt. It is a tool for real progress rather than just a temporary fix.
The platform is designed to be user-friendly and transparent. You can check your rate without worrying about a sudden drop in your credit score. This is particularly useful for people with fluctuating incomes who need to know exactly what terms they qualify for before committing.
Pros:
- High maximum loan amounts up to $36,500.
- Checking your rate does not impact your credit score.
- Flexible purposes including travel, weddings, or taxes.
Cons:
- Specific approval requirements are not fully detailed.
2. JetzLoan
JetzLoan enters the arena as a specialized option for those needing quick movement. While the specific details of their current offerings are best confirmed through their direct portal, they are positioned as a streamlined solution for modern borrowers. They cater to the digital-native borrower.
This is someone who expects an application process that takes minutes, not hours. They want to manage their entire relationship with the lender via a mobile interface. If you live your life through a smartphone, this style of lending feels much more natural.
Finding a lender that understands the urgency of a modern lifestyle is key. They aim to provide a bridge for those who cannot afford to wait weeks for a decision from a traditional big-box bank. Traditional banks often require in-person signatures and mountains of paperwork that slow everything down.
For a person whose car has broken down and whose job requires reliable transportation, the speed JetzLoan aims for can be the difference between staying employed and losing a paycheck. It is about keeping your life moving forward.
Pros:
- Streamlined application process.
- Targeted at quick-turnaround needs.
Cons:
- Limited public data on specific loan amounts.
3. MoneyLion
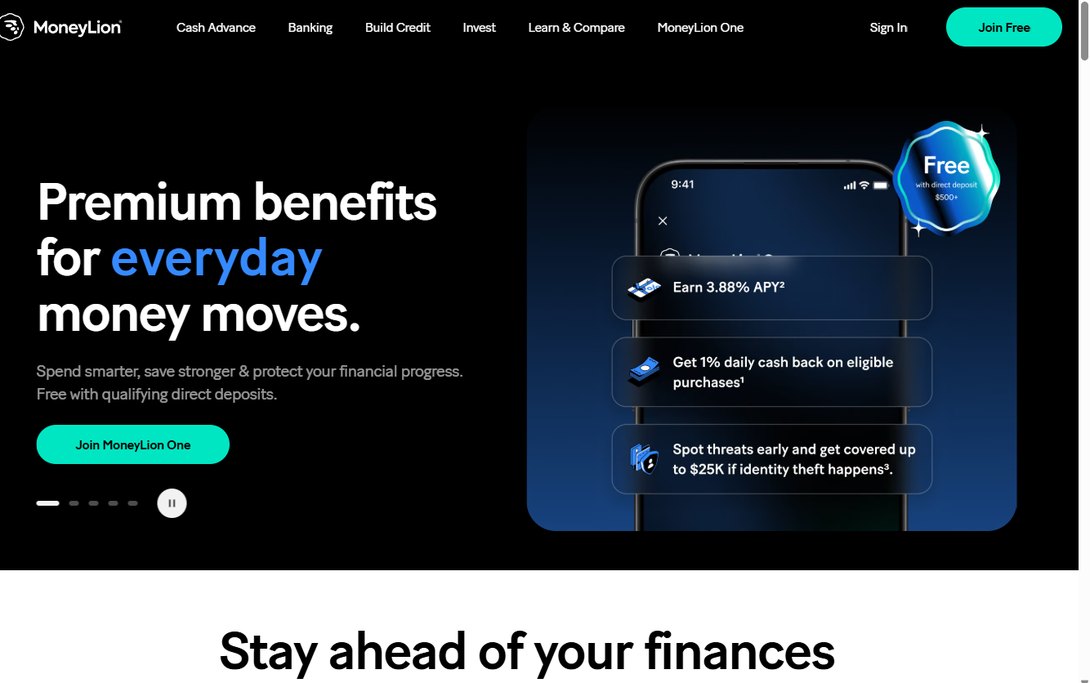
MoneyLion is a powerhouse for those who want a comprehensive financial ecosystem. They offer everything from small cash advances to massive personal loans reaching up to $100,000. It is a versatile tool for both daily survival and long-term planning.
Instead of just being a one-off transaction, MoneyLion acts more like a digital bank. They provide a suite of tools designed to keep your finances in check over the long haul. It is about building a relationship rather than just taking a loan.
What sets them apart is the ability to build credit while you borrow. Their Credit Builder Plus feature is a lifesaver for someone trying to climb out of a credit hole. By reporting your on-time payments to the major credit bureaus, they help you strengthen your profile.
This helps you prepare for future, lower-interest opportunities like mortgages or auto loans. They provide the tools to manage today and plan for a much brighter tomorrow. It is a holistic approach to personal finance.
Pros:
- Extremely high loan ceiling of $100,000.
- Options to build credit through specialized products.
- Fast, expedited delivery options for cash.
Cons:
- Turbo fees may apply for expedited delivery.
- Requires qualifying direct deposits for certain benefits.
4. OppLoans
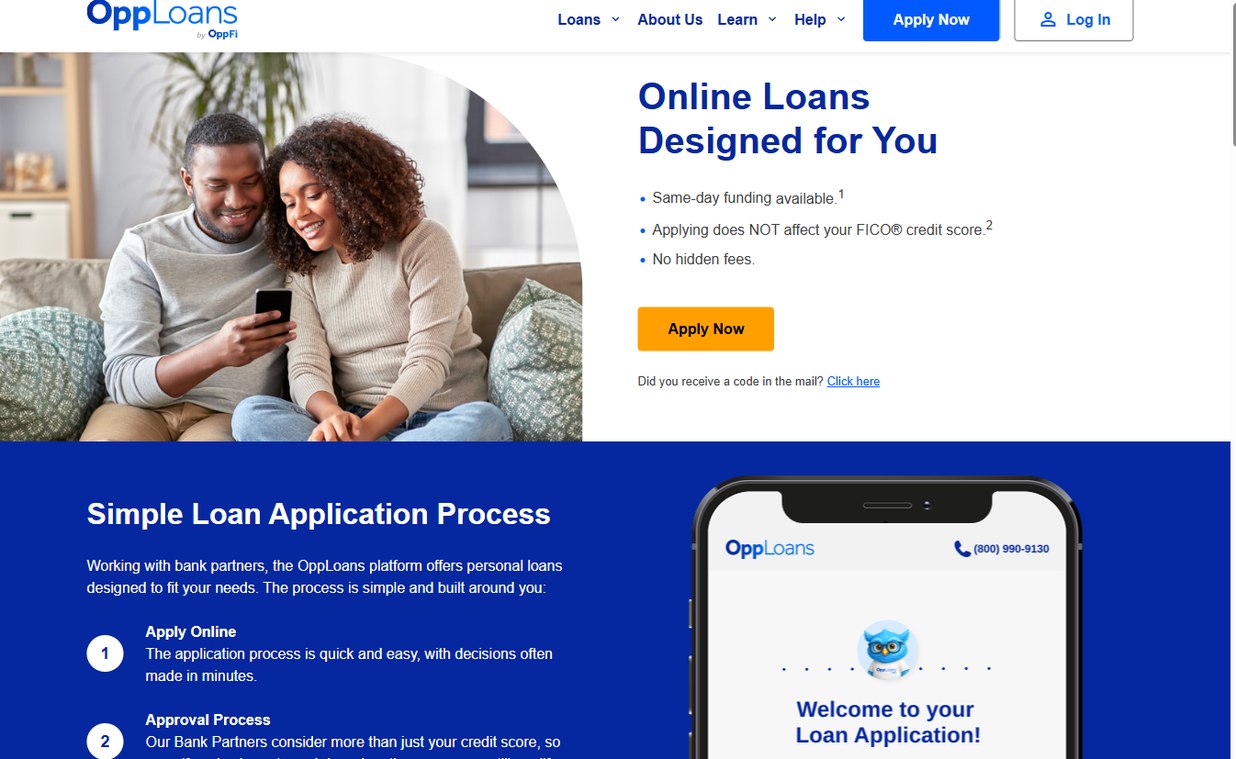
OppLoans has earned a reputation as a top-tier marketplace for those who might be turned down elsewhere. Their model is built around the idea that a credit score shouldn’t be the only factor in your financial story. They look at the bigger picture of your ability to pay.
They often consider your consistent income and employment history rather than just a three-digit number. This approach is why many find them a more equitable option than traditional banks. They see the person behind the score.
The speed of their service is impressive, with same-day funding available in many cases. This makes them a go-to for emergency expenses that cannot wait for a standard banking cycle to complete, such as an emergency plumbing repair or a sudden hospital bill.
They act as a vital buffer for those living paycheck to paycheck who experience a temporary, unexpected shock to their budget. When life throws a curveball, they are there to catch it.
Pros:
- High research-based rating for no-credit-check loans.
- Does not affect your FICO credit score to apply.
- Potential for same-day funding.
Cons:
- Approval is subject to bank partner criteria.
5. Check City
Check City operates as a versatile provider of short-term liquidity. They offer a variety of products, including payday loans, installment loans, and personal loans. This variety allows you to choose the structure that fits your specific repayment capacity.
If you have a very short-term cash gap, like needing $300 to cover rent until Friday, a payday-style product might suffice. If you need a larger amount to be paid back over months, their installment loans are the better path. You pick the tool for the job.
If you need money right now, their payday loan option is a fast-acting solution. However, for those who prefer a more manageable pace, their installment loans break payments into smaller, digestible chunks. This flexibility is essential for managing cash flow.
The “best” loan is entirely dependent on your specific situation. You have to consider your ability to repay the principal without taking on new debt just to pay off the old debt. It is a delicate balance to maintain.
Pros:
- Multiple loan types: payday, installment, and personal.
- Flexible repayment structures for installment loans.
- Easy online application process.
Cons:
- Payday loans can be very expensive due to short terms.
- Availability is limited to specific eligible states.
6. Lend You Cash
Lend You Cash is built for the “right now” moments. They focus on providing installment loans of up to $1,000 with a remarkably fast turnaround. You can often see those funds in your account by the next business day.
This makes them an excellent choice for bridge financing. These are small amounts of capital used to cover a gap that will be closed by an upcoming paycheck or tax refund. It is a quick fix for a temporary problem.
This is a specialized tool for unexpected expenses that are relatively small in scale. It is a quick fix for a temporary gap, rather than a long-term financial restructuring tool. Use it wisely to keep your finances steady.
Using this type of loan to pay off a much larger, higher-interest debt is generally not recommended. However, using it to cover a one-time emergency can prevent more serious consequences like late fees or utility shut-offs.
Pros:
- Fast funding by the next business day.
- Simple, direct application process.
- Clear focus on unexpected, smaller expenses.
Cons:
- Loan amounts are capped at a relatively low $1,000.
Avoid the trap of only looking at the monthly payment. A low monthly payment often means a much longer term, which can lead to paying significantly more in interest over time. A $5,000 loan with a 5-year term might have a very low monthly payment, but you could end up paying back $7,000 or more.
Always calculate the total cost of the loan before signing your name on the dotted line. You need to know exactly how much that money is costing you in the long run. Don’t let a low monthly number blind you to the total debt.
Another common pitfall is ignoring the impact on your credit score. Even if a lender doesn’t perform a hard inquiry, the debt itself will appear on your report. This credit utilization and debt-to-income ratio can affect your ability to get a mortgage or a car loan later.
Be mindful of how many open lines of credit you are managing at once. You want to avoid a cycle of debt where you are constantly borrowing just to pay off previous interest. It is a treadmill that is very hard to get off once you start running.
Finally, always verify the legitimacy of the lender. Scammers often pose as high-speed lenders to harvest your social security number or demand upfront fees before releasing a loan. Never pay an upfront fee to get a loan; legitimate lenders deduct fees from the loan proceeds.
Use resources like the Online Lenders Alliance if you encounter suspicious behavior or potential fraud. A little bit of due diligence today can save you a massive headache in the months to come. Protect yourself before you sign anything.
